The views expressed are those of the author.
Abstract
Algorithmic and artificial intelligence (AI)-driven trading systems are transforming financial markets. Existing regulatory frameworks appropriately focus on whether individual algorithms are tested, governed and controlled. However, systemic vulnerabilities may emerge when multiple independent systems respond similarly to the same market shock. This Policy Brief proposes reaction concentration as an additional supervisory lens: the degree to which economically significant automated market exposure is expected to move in the same direction within a defined market and time horizon after a common shock. Building on research on algorithmic trading, market microstructure, liquidity and systemic risk, it proposes a framework based on Algorithmic Response Profiles (ARPs), a proposed Reaction Concentration Index (RCI), response elasticity and latent stress liquidity demand analysis.
Regulators have made significant progress in supervising individual algorithms. Firms test systems, establish controls and monitor operational risks.
However, the next supervisory challenge is understanding collective behaviour.
The question should evolve from: “Is this algorithm controlled?” to: “How will many algorithms behave together during market stress?”
The literature points to a dual effect of automation on market quality. Hendershott, Jones and Menkveld (2011) find that algorithmic trading can narrow spreads and improve liquidity, while Easley, López de Prado and O’Hara (2012) show how toxic order flow can be associated with short-term volatility. Kirilenko et al. (2017), analysing the 2010 Flash Crash, further demonstrate how rapid interactions among market participants can contribute to extreme intraday dynamics. Brunnermeier and Pedersen (2009) provide a broader mechanism through which market and funding liquidity can reinforce one another and generate liquidity spirals.
Two studies highlighted by SUERF are particularly relevant to the argument developed here. Pojarliev and Levich (2011) propose a methodology for detecting crowded trades in currency funds and explicitly connect crowded positioning with risks to financial stability. Sánchez Serrano (2020), reviewing the high-frequency-trading literature from a systemic-risk perspective, identifies correlated positions, herd behaviour and the potential withdrawal of liquidity under stress among the key vulnerabilities. These contributions suggest that the relevant unit of analysis is not only the individual trading strategy, but also the concentration and synchronisation of behaviour across market participants.
Recent institutional research extends these concerns to AI-driven markets. The IMF’s October 2024 Global Financial Stability Report notes that algorithmic risk limits can become destabilising when they trigger simultaneously, creating feedback loops and sudden withdrawals of algorithmic liquidity. The Financial Stability Board (2024) identifies market correlations, third-party concentration, cyber risk, and model and data vulnerabilities as channels through which AI adoption could amplify systemic risk. ECB research by Anand, Kazinnik, Leonello and Panetti (2026) shows that different AI architectures can produce materially different patterns of coordination and fragility, making algorithm design itself relevant for financial stability.
BIS research also points to the need for system-level monitoring. Aliyev et al. (2024, revised 2026) find that algorithmic trading and market fragmentation can improve average liquidity while being associated with weaker liquidity resilience in some markets. In parallel, BIS Project Logos (2026), conducted with the Bank of England, Deutsche Bundesbank and the Eurosystem, is explicitly designed to study when LLM-based portfolio managers may amplify or dampen correlated decision-making in simulated markets. Taken together, this literature establishes a strong basis for monitoring crowding, common reactions and liquidity feedbacks, but it leaves room for a practical supervisory measure of how much economically significant automated exposure is likely to move in the same direction after a common shock. The reaction-concentration framework proposed in this brief is intended to address that measurement gap.
This Policy Brief proposes reaction concentration as an additional supervisory lens.
While prevous research has examined algorithmic trading risks and systemic risk separately, less attention has been given to measuring how much economically significant market exposure is programmed to move in the same direction after a common shock. The proposed framework is intended as a supervisory screening tool rather than a regulatory threshold.
Figure 1. Graphical Representation of the Argument
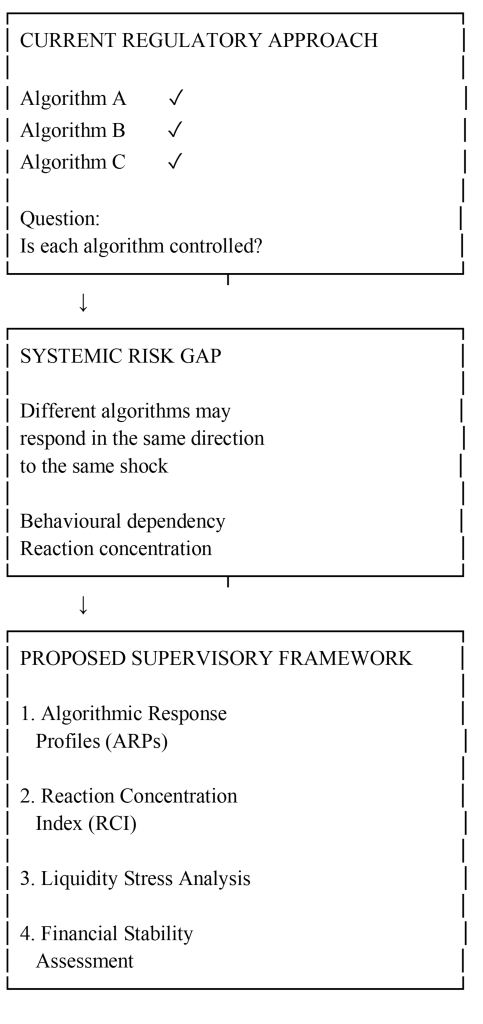
Algorithmic Response Profiles (ARPs):
Confidential profiles describing broad behavioural characteristics without requiring disclosure of proprietary source code.
Proposed Reaction Concentration Index (RCI):
An indicator that could help supervisors identify synchronized market reactions following common shocks.
Response Elasticity:
A measure of how strongly exposure changes when stress variables move.
Latent Stress Liquidity Demand:
An assessment of potential liquidity pressure when multiple automated systems reduce risk simultaneously.
Traditional approach:
System-level approach:
The future risk of algorithmic markets may not come from a defective algorithm. It may come from thousands of well-designed algorithms reaching the same conclusion at the same moment. Financial supervision should therefore evolve from asking whether an algorithm is safe toward asking whether the market remains resilient when algorithms behave safely together.
Pojarliev, M., & Levich, R. M. (2011). Detecting Crowded Trades in Currency Funds. Financial Analysts Journal, 67(1), 26–39. doi:10.2469/faj.v67.n1.2
Sánchez Serrano, A. (2020). High-Frequency Trading and Systemic Risk: A Structured Review of Findings and Policies. Review of Economics, 71(3), 169–195. doi:10.1515/roe-2020-0028
Hendershott, T., Jones, C. M., & Menkveld, A. J. (2011). Does Algorithmic Trading Improve Liquidity? The Journal of Finance, 66(1), 1–33. doi:10.1111/j.1540-6261.2010.01624.x
Kirilenko, A., Kyle, A. S., Samadi, M., & Tuzun, T. (2017). The Flash Crash: The Impact of High Frequency Trading on an Electronic Market. The Journal of Finance, 72(3), 967–998. doi:10.1111/jofi.12458
Easley, D., López de Prado, M. M., & O’Hara, M. (2012). Flow Toxicity and Liquidity in a High-Frequency World. The Review of Financial Studies, 25(5), 1457–1493. doi:10.1093/rfs/hhs053
Brunnermeier, M. K., & Pedersen, L. H. (2009). Market Liquidity and Funding Liquidity. The Review of Financial Studies, 22(6), 2201–2238. doi:10.1093/rfs/hhn098
Acemoglu, D., Ozdaglar, A., & Tahbaz-Salehi, A. (2015). Systemic Risk and Stability in Financial Networks. American Economic Review, 105(2), 564–608. doi:10.1257/aer.20130456
Aliyev, N., Aquilina, M., Rzayev, K., & Zhu, S. (2024; revised 2026). Through Stormy Seas: How Fragile Is Liquidity Across Asset Classes and Time? BIS Working Papers No. 1229. BIS Working Paper No. 1229
International Monetary Fund. (2024). Advances in Artificial Intelligence: Implications for Capital Market Activities. In Global Financial Stability Report, October 2024, Chapter 3. IMF GFSR, Chapter 3
Financial Stability Board. (2024). The Financial Stability Implications of Artificial Intelligence. FSB report
Anand, K., Kazinnik, S., Leonello, A., & Panetti, E. (2026). Financial Stability in the Age of Artificial Intelligence: The Role of Algorithmic Architecture. ECB Research Bulletin No. 143 / Working Paper No. 3225. ECB Research Bulletin
Bank for International Settlements. (2026). Project Logos: Observing the Behaviour of LLM-Based Agents in a Simulated Financial Market Environment. BIS Project Logos